No One Told Me Medicare Isn't One Signup
Direct answer
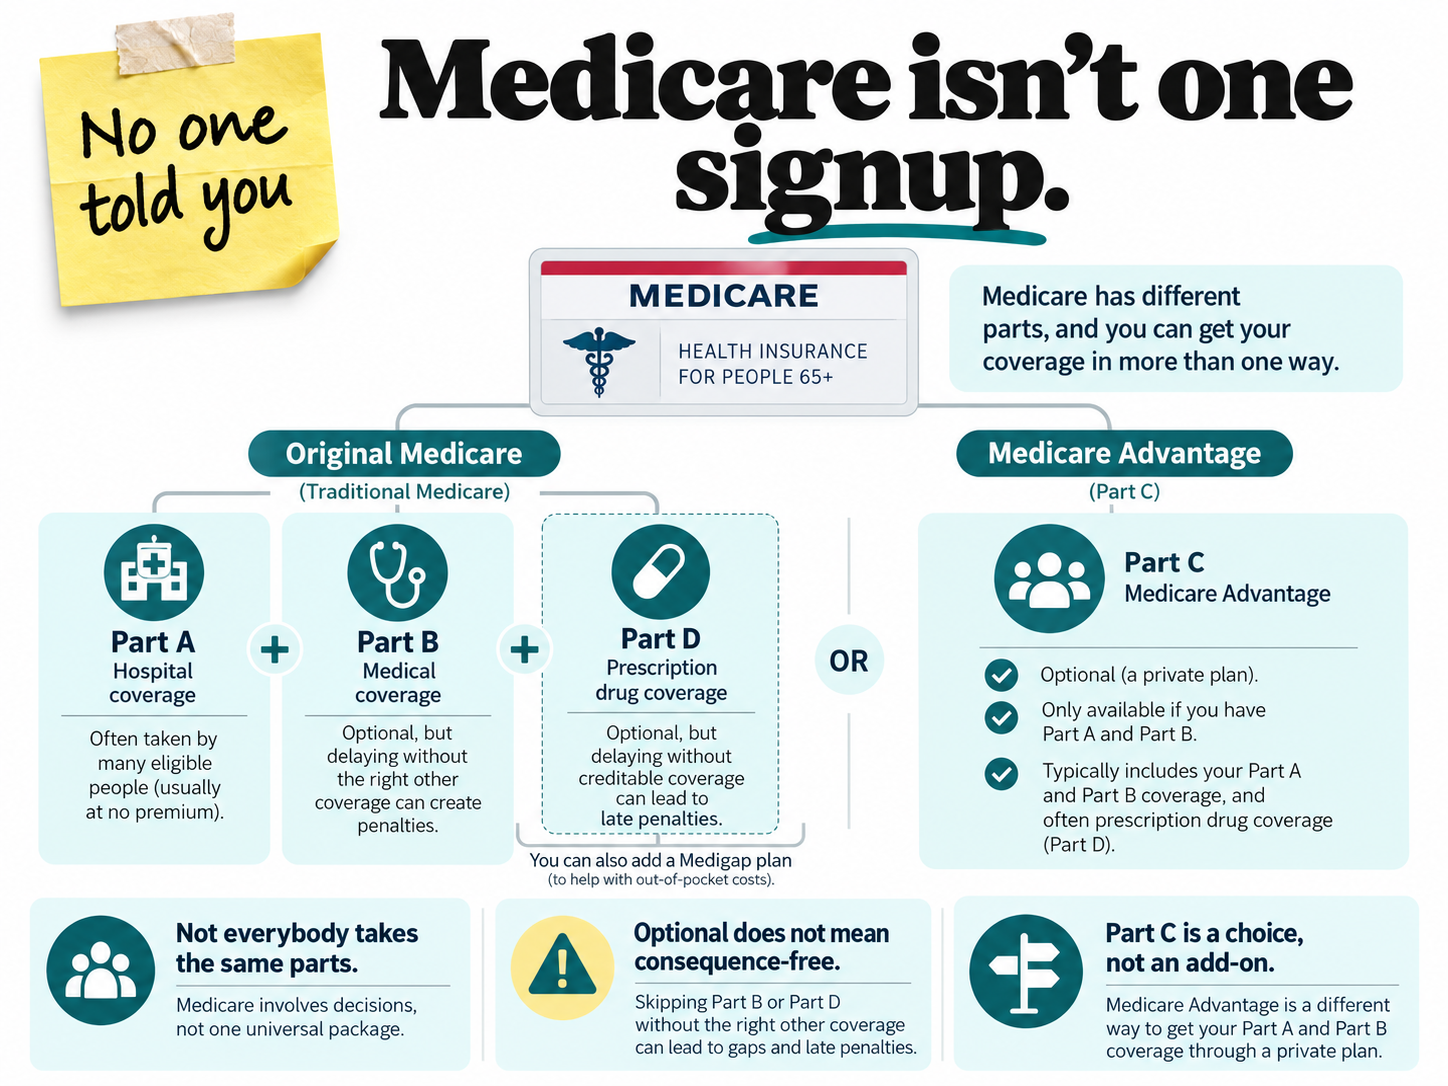
No. You do not have to enroll in every part of Medicare.
Part B is optional.
Part D is optional.
Medicare Advantage, Part C, is optional.
But skipping Part B or Part D without the right other coverage can create coverage gaps and late-enrollment penalties later.
Part C is only for people who choose Medicare Advantage, and you must have Part A and Part B to join it.
Updated
Wait. I do not just "sign up for Medicare"?
Not exactly.
There is not one universal Medicare package where everybody signs one form and gets the same coverage.
You have decisions to make.
What about Part A?
Part A is hospital and inpatient coverage.
Most people qualify for premium-free Part A because they or a spouse paid Medicare taxes long enough.
Many people take Part A when eligible.
Some people are enrolled automatically.
There are situations where Part A timing matters, especially if you are still working and contributing to an HSA.
Do I have to take Part B?
No.
Part B is optional.
It covers doctors and outpatient medical care.
But if you skip Part B without qualifying coverage from current employment, you can face a late-enrollment penalty later and may have to wait for an enrollment period.
Optional does not mean consequence-free.
Do I have to take Part C?
No.
Medicare Advantage is optional.
It is an alternative way to get Part A and Part B.
To join it, you must have Part A and Part B.
Do I have to take Part D?
No.
Part D prescription-drug insurance is optional.
But if you go 63 days or more without Part D or other qualifying prescription-drug coverage, you can face a late-enrollment penalty later.
Again:
Optional does not mean consequence-free.
So what do people actually enroll in?
Common Original Medicare setup:
Part A + Part B + Part D
Some people also buy Medigap.
Common Medicare Advantage setup:
Part A + Part B + Part C
Most Part C plans also include Part D.
You still generally pay the Part B premium when you are in Medicare Advantage.
What if I am still working at 65?
Slow down before automatically enrolling or automatically delaying.
Your own or your spouse's current employer coverage, prescription coverage, employer size and HSA contributions can affect what you should do.
The bottom line
You do not have to buy every Medicare letter.
But do not casually skip Part B or Part D just because they are technically optional.
Before you decline anything, know:
what coverage you have now
whether Medicare lets you safely delay
whether a penalty could apply later
when your current coverage ends