What Happens If You Sign Up for Medicare Late?
Direct answer
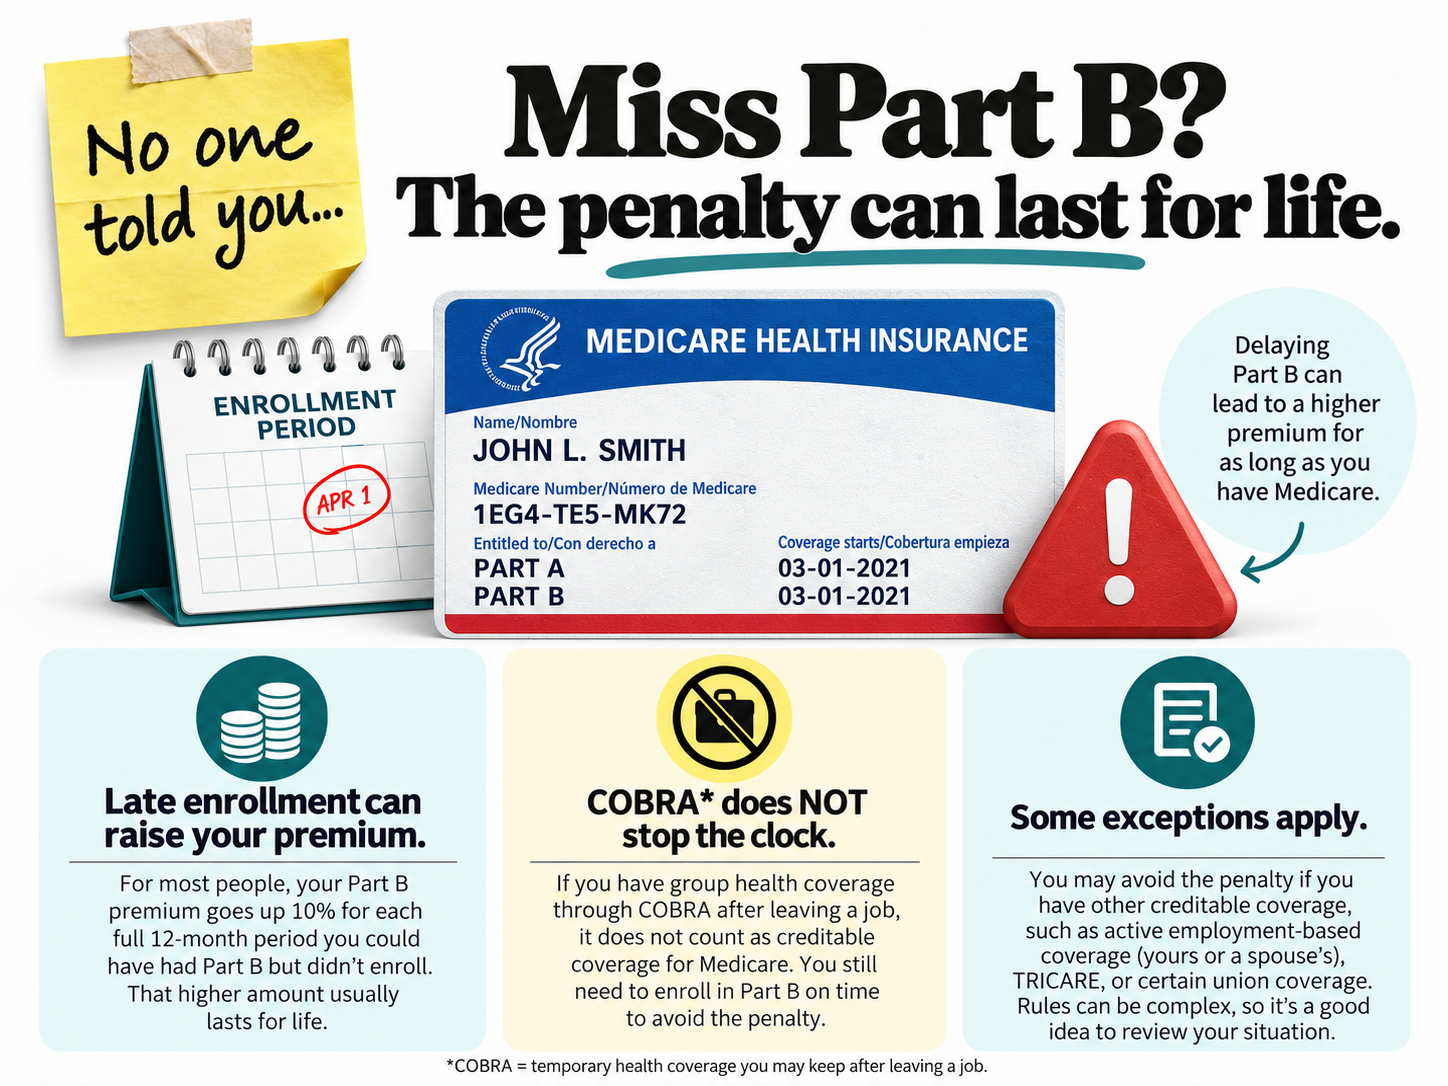
You can end up paying a penalty for Medicare for the rest of your life. If you miss the deadline to enroll in Part B and do not qualify for an exemption, Medicare generally adds 10% to your Part B premium for every full 12 months you were late. Even if you have COBRA through your last job, it does not stop this clock.
Updated
The short version
Medicare has deadlines.
Missing one can cost you for years.
This matters most for people who keep working past 65 or leave a job after 65 and assume they can deal with Medicare later.
Sometimes you can delay Medicare safely.
Sometimes you cannot.
The important question is what kind of health insurance you have.
What happens if I am late?
If you should have signed up for Part B and did not, Medicare generally adds 10% to your monthly Part B premium for every full 12-month period you were late.
If you were late by two full years, the penalty is generally 20%.
And unlike a parking ticket, this is not usually a one-time charge.
The higher premium can last as long as you have Part B.
What does “qualify for an exemption” mean?
Medicare usually calls this qualifying for a Special Enrollment Period.
The most common example is continuing to have qualifying health coverage through your own or your spouse’s current job after age 65.
If that applies, you may be able to delay Part B without the late penalty.
When the job or that job-based coverage ends, you generally get an eight-month Special Enrollment Period to enroll in Part B.
You do not need to memorize the term.
Just know that certain situations let you enroll later without being treated as late.
What if I am still working at 65?
If you or your spouse are still actively working and you have qualifying health insurance from that current job, you can often wait to sign up for Part B.
When that job or job-based health insurance ends, the Medicare clock starts.
That is the moment to pay attention.
What if I have COBRA?
This is the trap.
COBRA lets you keep the health insurance you had through your old job.
So it feels like nothing changed.
But Medicare does not treat COBRA as coverage from a current job.
Your Part B Special Enrollment Period generally starts when the job or job-based coverage ends.
The Medicare clock keeps moving even while COBRA continues.
What people get wrong
“I still have my old employer insurance through COBRA, so I can wait.”
That is the dangerous assumption.
You still have health insurance.
But Medicare does not consider COBRA the same thing as insurance based on current employment for this Part B enrollment rule.
The COBRA clock and the Medicare clock are different.
Why this matters before you leave a job
If you are 65 or older and thinking about retiring, do not wait until your last day of work to figure out Medicare.
Before you leave, find out:
- when your employer health insurance ends
- whether you already have Part A
- when Part B needs to start
- whether COBRA makes sense
- what happens to your prescription coverage
The dates matter.
The bottom line
You can have perfectly good COBRA health insurance and still miss your Medicare Part B enrollment deadline.
If you remember one thing from this article, remember:
COBRA does not stop the Medicare clock.